Your first auto policy arrives looking like a vocabulary quiz nobody warned you about. There are declarations, endorsements, limits stacked in pairs of numbers, and a premium at the bottom that you understand perfectly well, because it is the part you have to pay. Everything above it feels like background noise. It is not.
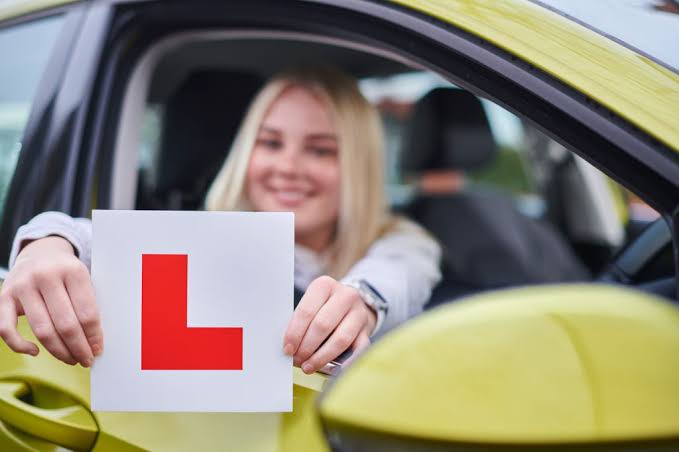
The language is dull by design, drafted by lawyers and regulators rather than by anyone trying to hold your attention. The words still carry money. Knowing what a deductible does, or where liability stops and collision begins, separates a claim that goes smoothly from a bill you never saw coming. New drivers already pay the steepest rates in the market, so they have the most to gain from reading the fine print once, slowly.
Here is a plain reading of the terms you will actually meet, with small examples that make them stick.
Premiums, Deductibles, and the Money That Actually Moves
A premium is the price of the policy, paid monthly or once a year, and it reflects your age, your driving record, the car you chose and the postal code where it sleeps. A deductible is different. It is the slice of a claim you absorb yourself before the insurer pays anything, and five hundred dollars is a common figure. Say a hailstorm leaves you with a twenty four hundred dollar repair bill and your deductible is five hundred. You pay that five hundred, the insurer covers the remaining nineteen hundred. Raising the deductible lowers the premium, which sounds like free money until the day you claim.
Liability Coverage Is the Part the Law Cares About
Liability pays for the damage and injury you cause other people, not for your own car. Ontario sets a floor here: every registered vehicle must carry at least two hundred thousand dollars in third party liability, and the province says plainly that collision coverage for your own vehicle is a good idea but not the law. The Insurance Bureau of Canada lists the same mandatory package for Ontario drivers, adding accident benefits and uninsured automobile coverage to that liability minimum. Most brokers will still steer you toward one or two million, because a serious injury claim burns through two hundred thousand quickly.
Collision and Comprehensive Cover Two Different Kinds of Bad Day
Collision responds to impact, whether you hit another car, a guardrail or a light standard. Comprehensive handles the rest of the catalogue: theft, fire, vandalism, hail, a branch coming down in a windstorm. Theft is not an abstract worry in this province. Équité Association’s Ontario ranking put one generation of the Lexus RX at two thousand and eighty three thefts, a 9.4 percent theft rate across insured vehicles. If you financed or leased the car, your lender almost certainly requires both coverages, so the choice may already be made for you.
Policy Limits and Exclusions Define the Edges of Your Coverage
A limit is the most your insurer will pay on a given coverage. An exclusion is something the policy never covers at all, and the usual suspects are racing, deliberate damage, commercial delivery work on a personal policy, and a driver who was never listed on the file. Endorsements buy some of that ground back for a fee. Insurance rewards the same discipline that accounting does, which is keeping records that hold up under scrutiny, so save your declarations page, your repair invoices and every photo you take at the roadside.
Comparing Quotes Without Guessing
Compare quotes the way an accountant would, line against line: identical limits, identical deductibles, identical optional coverages. Geography moves the number too, so a driver pricing Ottawa auto insurance will see figures that look nothing like a quote written for a small northern town. Then ask about the discounts nobody volunteers, including winter tires, bundling with a tenant policy, telematics programs and staying listed on a parent’s policy while you build history.
None of this makes the paperwork enjoyable. It does make it legible, and legible is enough. Once you can name the parts, a renewal notice stops being a mystery and becomes a short list of decisions about how much risk you want to hold yourself.
Start with the coverage the law requires, decide what your savings account could absorb on a bad week, and set the deductible there rather than wherever the cheapest quote lands. Ask your broker to explain any term twice if the first answer sounds rehearsed. Good ones expect that.
The first year of driving is expensive almost everywhere, and no amount of vocabulary changes that. Understanding the words simply means you stop paying for things you do not need, and stop assuming protection you never actually bought.